Market Updates
CY
12 June 2026
银保业务佣金结构迎巨变 Major Shifts in Bancassurance Commission Structures
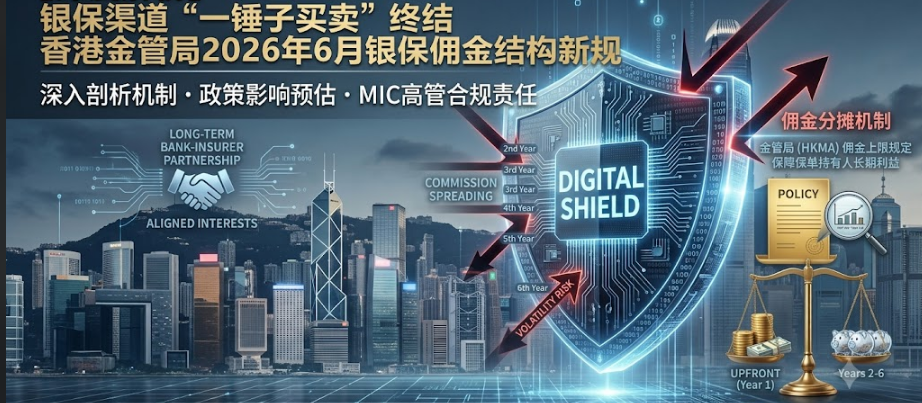
银保渠道“一锤子买卖”终结:深度解析香港金管局2026年6月银保佣金结构新规
The End of "One-Off Deals" in Bancassurance: A Deep Dive into the HKMA’s June 2026 New Commission Spreading Rules
香港金融管理局(HKMA)于 **2026年6月5日** 正式发出了《关于获授权机构作为持牌保险中介人销售定期保费分红保单的薪酬结构》的重磅通函。该新规全面对接了保监局(IA)早前的监管逻辑,旨在通过强制性的“佣金分摊”(Commission Spreading)机制,将银行、前线员工与投保人的长期利益深度绑定。
Hong Kong Monetary Authority (HKMA) issued a landmark circular on **June 5, 2026**, titled *"Remuneration Structures of Licensed Insurance Intermediaries which are Authorized Institutions for Participating Policies with Regular Payment Terms."* Aligning closely with the prior regulatory framework of the Insurance Authority (IA), this new mandate introduces a compulsory **"Commission Spreading"** mechanism designed to structurally tie the long-term interests of banks and frontline staff to those of policyholders.
一、 新规核心:佣金分摊的两步走时间表与硬性比例 The Core Mandate: Two-Phase Timeline and Strict Caps
本次金管局新规的打击焦点非常明确——彻底粉碎“首期高额回扣/佣金”的驱动模式。新规针对**定期保费的分红人寿保险保单(Participating Policies with Regular Payment Terms)**,设定了极具约束力的佣金支付上限及分摊要求:
The HKMA’s new regulation directly targets the traditional "front-loaded" commission payment structure. For **participating life insurance policies with regular premium payment terms**, the regulatory body has established highly restrictive caps and spreading requirements:
实施阶段 Implementation Phase
第一阶段:2027年7月1日起,首期(第一保单年度)佣金上限不得超过总佣金的 85%,剩余15%或以上,必须在至少五年内(或较短的保费缴付期内)平均分摊(即第2至第6保单年度每年收取的金额必须完全相同)。
Phase I:From July 1, 2027 . Upfront (1st Policy Year) Commission Cap shall not exceed 85% of total commission. The remaining 15% or more must be spread evenly over a minimum of **five years** (or the premium payment term, whichever is shorter), meaning identical amounts must be received from the 2nd to the 6th policy years.
第二阶段:2028年7月1日起,首期(第一保单年度)佣金上限不得超过总佣金的70%,剩余30%或以上,必须在至少五年内平均分摊。
Phase II:From July 1, 2028 . Upfront (1st Policy Year) Commission Cap shall not exceed 70% of total commission. The remaining 30% or more must be spread evenly over a minimum of five years (or the premium payment term, whichever is shorter), meaning identical amounts must be received from the 2nd to the 6th policy years.
核心原则:这一递进式政策给市场留出了缓冲期,但最终目标是确保至少30%的佣金收入必须在未来五年内“细水长流”地释放。
Core Philosophy:This progressive approach provides the market with a transitional buffer, but the ultimate destination is unequivocal: at least **30%** of commission revenues must be distributed as a "steady trickle" across half a decade.
二、 打破盲区:“实质重于形式”的穿透式监管 Closing the Loop: The "Substance-over-Form" Approach
新规不仅约束“银行(持牌法人)从保险公司收取的佣金”,更直接穿透至“银行支付给前线业务代表(Technical Representatives, TR)的薪酬结构”。
The scope of this circular goes far beyond the top-line commission paid by insurance companies to banks (AIs). It explicitly penetrates down to the **remuneration structures of individual Appointed Technical Representatives (TRs)** on the frontline.
在过去,部分持牌机构试图通过“销售奖金(Bonus)”、“绩效记分卡(Scorecard)”或“业务量提成”等名目绕开佣金限制。对此,金管局在新规中祭出了“实质重于形式”(Substance-over-Form)的穿透式监管原则:
Historically, some institutions attempted to bypass commission restrictions by reclassifying volume-driven payouts as "quarterly performance bonuses," "sales scorecards," or "premium volume incentives." To neutralize this loophole, the HKMA applies a strict "Substance-over-Form" doctrine:
1. 全口径纳入:无论前线代表的奖金被称为“佣金”、“季度奖”还是“保费生成返点”,只要该笔收入的计算主要或完全取决于销售业务量(Business Volume),就必须一体适用上述分摊要求。
1. All-Inclusive Scope:** Regardless of whether frontline compensation is labeled a "commission," "bonus," or "premium generation incentive," if its calculation depends primarily or solely on business volume, it must strictly comply with the aforementioned spreading schedules.
2. 免除豁免门槛:*只有当银行的记分卡高度融合了客观的“非财务表现指标”(如客户满意度、保单持续率、合规合规审计结果),且该奖金不纯粹与销售额挂钩时,方可申请豁免分摊。一旦被认定合规评估未达标,银行必须强制对员工实施佣金分摊。
2. The Exemption Threshold: A bonus or scorecard component can only be exempted from the spreading rules if the bank can demonstrate that its scorecard integrates robust, objective "non-financial performance metrics" (e.g., customer satisfaction, policy persistency rates, and compliance audit results) that exert material influence over the final payout. If a scorecard fails this regulatory scrutiny, the TR's remuneration must be forcefully spread.
三、 行业重塑:对银行与保险公司的三大长期冲击 Industry Reshaping: Three Long-Term Impacts on Banks and Insurers
1. 银行财富管理收入面临“财务休克期” A Temporary "Financial Shock" to Wealth Management Fees
由于首期佣金比例从过去可能高达90-100%下降至70%,各大银保合作银行在2027-2028年将迎来阶段性的中介手续费收入(Fee Income)下滑。虽然总佣金并没有减少,但财务确认(Revenue Recognition)的递延,将考验银行短期内的盈利中枢和KPI考核体系。
With upfront commissions dropping from historical heights of 90-100% down to a strict 70% cap, bancassurance banks will face a structural dip in accounting fee income during the 2027–2028 transition. While the nominal cumulative commission remains intact, the deferral of revenue recognition will inevitably strain short-term return-on-equity (ROE) metrics and force a complete overhaul of internal banking KPIs.
2. 产品设计倒逼“客户利益导向” Product Engineering Forced Toward "Client-Centricity"
保险公司在设计银保专供产品时,必须重新测算现金流与现金价值。由于无法再用高额首期佣金“重赏”渠道,产品必须依靠更优的长期红利实现率、更合理的退保费用(Surrender Charges)以及真正契合银行客户需求的保障条款来赢得市场。
Insurers will be forced to re-engineer products tailored for the bancassurance channel, recalculating asset-liability matches and cash value accumulation curves. Deprived of the ability to use massive upfront incentives to entice distributors, products must compete on superior long-term dividend fulfillment ratios, reasonable surrender charges, and protection riders that genuinely meet the needs of bank clients.
3. 前线销售团队面临大洗牌 A Shakeup of Frontline Sales Talent
传统的“快钱”销售人员将面临巨大的生存压力。相反,具备长期客户陪伴能力、能提供持续售后服务的财富管理顾问将成为各大银行争夺的香饽饽。这也将从根本上降低由于员工离职(Orphan Policies)带来的保单孤儿化及后续投诉风险。
Frontline personnel accustomed to chasing high-volume, quick-turnover sales will experience severe financial friction. Conversely, wealth advisors who possess deep relationship management skills and excel at providing continuous post-sale advisory will become highly sought-after assets. This structural shift will substantially reduce the risk of "orphan policies" and subsequent complaints stemming from employee turnover.
四、 机构落地指引与下一步行动 Institutional Implementation Guidance & Next Steps
金管局要求所有获授权机构(AIs)必须立刻行动,在过渡期内完成以下合规整改:
The HKMA expects all Authorized Institutions (AIs) to take immediate action to ensure total compliance during the countdown period:
重构中介协议: 与合作保险公司重新谈判佣金支付条款,确保2027年后的合同完全符合分摊比例。Reconstruct Intermediary Agreements:** Renegotiate commission schedules within distribution contracts with partner insurance companies to guarantee that all post-2027 sales structurally reflect the new ratios.
改造薪酬系统(Payroll Systems):升级内部HR与财务系统,使其具备跨越5年进行前线TR佣金精细化记账、分摊发放及离职追溯(Clawback)的能力。Upgrade Payroll & HR Infrastructure: Modernize internal HR and financial accounting systems to support multi-year tracking, pro-rata amortization, and clawback mechanisms for individual TR commission lines.
优化监控与治理解构:重新审视现行销售代表的记分卡机制。若不想适用分摊,必须向金管局证明该“非财务指标”在薪酬决定中具备足够的实质影响力,以满足“公平对待客户”(Treating Customers Fairly)原则。
Refine Governance & Scorecard Frameworks:Review existing TR balanced scorecards. To maintain any volume-based exemptions, banks must rigorously document and prove to the HKMA that non-financial quality metrics carry genuine weight, upholding the core principle of **"Treating Customers Fairly".
原文链接/Source:
https://brdr.hkma.gov.hk/eng/doc-ldg/docId/getPdf/20260602-4-EN/Remuneration%20structures%20for%20licensed%20insurance%20intermediaries%20which%20are%20AIs.pdf