Market Updates
CY
5 July 2026
2025年资产及财富管理活动调查观察/Insight of Survey on Asset and Wealth Management Activities in Hong Kong 2025
证券及期货事务监察委员会(证监会)7月2日发布《2025年资产及财富管理活动调查》,显示香港作为领先的全球资产及财富管理枢纽于2025年表现出色,以下为要点总结及观察。
On July 2, the Securities and Futures Commission (SFC) released the *Survey on Asset and Wealth Management Activities in Hong Kong 2025*, revealing the outstanding performance of Hong Kong as a leading global asset and wealth management hub in 2025. The following is a summary of key points and observations.
一、 要点总结 (Summary of Key Highlights)
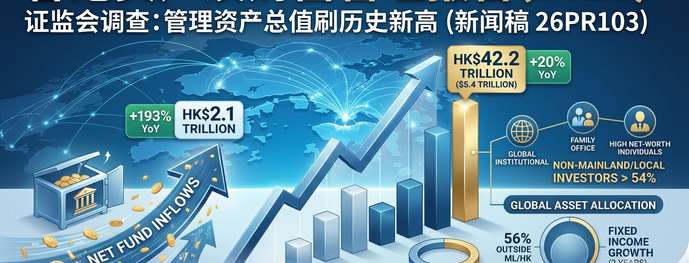
1. 核心数据概述 (Core Data Overview)香港证券及期货事务监察委员会(证监会,SFC)于2026年7月2日发布《2025年资产及财富管理活动调查》。报告显示,截至2025年底,香港的资产及财富管理业务管理资产总值(AUM)同比大幅增长20%,达到42.2万亿港元(约合5.4万亿美元),一举创下历史新高,打破了2021年35.5万亿港元的前期高位。推动这一历史性增长的核心动力来自于极具爆发力的净资金流入——2025年全行业净资金流入达2.1万亿港元(约合2650亿美元),同比剧增193%,实现连续第三年净流入增长。
On July 2, 2026, the Hong Kong Securities and Futures Commission (SFC) released its Asset and Wealth Management Activities Survey 2025. The report highlights that Hong Kong's total assets under management (AUM) jumped 20% year-on-year (YoY) to a record high of HK$42.2 trillion (US$5.4 trillion) as of end-2025, surpassing the previous peak of HK$35.5 trillion in 2021. The primary driver behind this milestone was a remarkable surge in net fund inflows, which skyrocketed by 193% YoY to HK$2.1 trillion (US$265 billion), marking the third consecutive year of expansion.
2. 细分板块与基金市场表现 (Segmental Breakdown & Fund Market Performance)
从业务板块来看,资产管理及基金顾问业务AUM同比增长19%至31万亿港元;私人银行及私人财富管理业务表现更为强劲,AUM同比大幅增长24%至12.9万亿港元。此外,获证监会认可的香港注册基金净资产值在2025年增长38%至2.3万亿港元,且这一强劲势头延续至2026年,截至2026年5月底进一步增至2.6万亿港元;2025年此类基金的净资金流入翻倍有余,达到3570亿港元。
Across major business segments, the AUM of asset management and fund advisory grew 19% YoY to HK$31 trillion, while private banking and private wealth management surged by 24% YoY to HK$12.9 trillion. Meanwhile, SFC-authorised Hong Kong-domiciled funds saw their net asset value rise 38% to HK$2.3 trillion by end-2025, a momentum that carried into 2026 with a further 13% increase to HK$2.6 trillion by end-May 2026; net fund inflows into these funds more than doubled to HK$357 billion in 2025.
3. 资金来源与资产配置结构 (Capital Sources & Asset Allocation Dynamics)
香港资产管理业展现出高度的国际化与机构化特征。来自中国内地及香港以外地区的投资者资金长期占据总AUM的54%以上,彰显了其全球辐射力。在资产配置方面,资产管理机构展现出卓越的全球化配置与抗风险能力,2025年有56%的资产投资于内地及香港以外的市场。同时,非股票类资产占比在过去五年提升了7个百分点至58%,债券投资连续两年实现双位数增长,反映出市场在应对全球宏观波动时的多元化防御策略。
Hong Kong's asset management sector demonstrated strong internationalisation and institutional focus. Non-Mainland and non-local investors consistently contributed over 54% of total AUM, underscoring the city's international appeal. In terms of allocation, portfolio managers displayed strong global diversification capabilities, investing 56% of AUM outside the Mainland and Hong Kong in 2025. Furthermore, the share of non-equity investments rose 7 percentage points over five years to 58%, with fixed-income assets recording double-digit growth for two straight years, reflecting strategic risk mitigation amid global macroeconomic shifts.
4. 行业生态与国际权威验证 (Market Ecosystem & External Validation)
报告指出,中资背景资产管理机构在港表现亮眼,AUM增长28%至3.9万亿港元,净资金流入飙升80%。开放式基金型公司(OFC)注册数量同比增长43%,持有9类(资产管理)牌照的机构数量增至2,358家(+7%),持牌人员增至15,747人(+5%)。波士顿咨询公司(BCG)《2026全球财富报告》亦佐证,香港在2025年以2.9万亿美元的跨境财富规模,跃居全球最大的跨境财富管理中心。
Mainland-related firms in Hong Kong outperformed overall market growth with a 28% YoY increase in AUM to HK$3.9 trillion, backed by an 80% surge in net inflows. Open-ended fund companies (OFCs) expanded by 43% YoY, while Type 9 (asset management) licensed firms grew 7% to 2,358, accompanied by a 5% increase in licensed individuals to 15,747. These findings align with Boston Consulting Group’s (BCG) Global Wealth Report 2026, which ranked Hong Kong as the world's largest cross-border wealth center in 2025, managing US$2.9 trillion in cross-border wealth.
二、 观察 (Insights)
1. 破纪录增长背后的资本逻辑 (Capital Logic Behind the Record Growth)香港资产管理规模突破42.2万亿港元历史新高,并非偶然的周期性反弹,而是全球地缘政治重塑与中西资本再平衡共同作用的结果。在全球加息周期尾声及地缘政治摩擦背景下,全球家族办公室和机构投资者对于安全、高效且监管透明的跨境财富避风港需求大幅增加。香港凭藉“一国两制”下的独特法律体系、资金自由流动性,以及完善的金融基础设施,成功吸引了大量中东、东南亚及欧洲增量资金的流入,验证了其作为国际金融中心的不可替代性。
The surge in Hong Kong's AUM to a record HK$42.2 trillion is not merely a cyclical rebound, but the result of global geopolitical realignment and capital rebalancing. As the global rate-hike cycle matured and geopolitical frictions persisted, global family offices and institutional investors sought highly secure, fluid, and transparent hubs for cross-border wealth. Hong Kong, leveraging its unique common-law framework under "One Country, Two Systems," free flow of capital, and robust market infrastructure, successfully captured incremental capital from the Middle East, Southeast Asia, and Europe, proving its irreplaceable status as a premier global financial hub.
2. 国际化基石与非对称依赖风险的厘清 (International Foundation & Refutation of Asymmetric Dependency)
值得注意的是,非内地及本地资金占比持续稳定在54%以上,这一数据有力驳斥了“香港金融市场完全中资化或本土化”的片面论调。它表明香港依然保持着极其强劲的全球吸引力,能够有效连接东西方资本。与此同时,中资机构AUM增长28%且净流入激增80%,表明香港正完美发挥“中资出海第一站”与“外资进入中国缓冲区”的双向枢纽功能,形成了双轮驱动的稳健资本生态。
Notably, non-Mainland and non-local capital consistently accounts for over 54% of total AUM. This figure effectively refutes the misconception that Hong Kong's financial market is becoming exclusively domestic or Mainland-reliant. It demonstrates that the city maintains strong global pull, seamlessly bridging East and West capital. Concurrently, a 28% growth in Mainland-backed institutions' AUM and an 80% surge in net inflows highlight Hong Kong's dual role as the premier springboard for Mainland capital going global and a strategic buffer for foreign capital entering China.
3. 资产配置结构的结构性演变 (Structural Evolution in Asset Allocation: Tilt Toward Fixed Income & Diversification)
资产管理者将56%的资金投资于内地及香港以外地区,且非权益类资产占比提升至58%,揭示了香港金融业面对复杂国际环境的成熟应变机制。过去高度依赖权益类资产(尤其是单一股票市场)的模式正在发生深刻改变。债券市场连续两年的双位数增长,以及对固收、私募股权、实物资产等多元化工具的倚重,表明香港正加速向全天候、全品类的综合性财富管理高地演进。
The allocation of 56% of AUM outside the Mainland and Hong Kong, combined with non-equity assets rising to 58%, reflects a mature risk-hedging mechanism among asset managers navigating macro volatilities. The legacy dependence on equity markets is giving way to a more balanced framework. Two consecutive years of double-digit growth in fixed-income investments, along with expanded exposure to private equity and real assets, signals Hong Kong's rapid transition into a resilient, all-weather asset allocation center.
4. 制度创新与生态建设的乘数效应 (Structural Innovations & Ecosystem Multiplier Effects)开放式基金型公司(OFC)数量大增43%,以及9类牌照机构和从业人员的稳步增长,凸显了香港监管层近年推行制度创新的政策红利。证监会对OFC及房地产投资信托基金(REITs)的资助计划、新资本投资者入境计划(New CIES)的实施,以及离岸人民币(RMB)中心建设,有效降低了基金设立门槛与运营成本。法治化环境与监管透明度,是香港击败竞争对手、登顶BCG全球跨境财富管理中心榜首的核心基石。
The 43% jump in registered OFCs, alongside steady growth in Type 9 licensed entities and professionals, underscores the strategic policy dividends driven by regulator-led reforms. The SFC’s grant schemes for OFCs and REITs, the rollout of the New Capital Investment Entrant Scheme (New CIES), and the expansion of the offshore RMB hub have significantly lowered fund structuring friction and costs. A robust legal framework coupled with regulatory clarity remains the foundational cornerstone enabling Hong Kong to secure its position as the world's top cross-border wealth center.
5. 前瞻展望与潜在挑战 (Forward-Looking Outlook & Potential Challenges: Objective & Balanced Perspective)
尽管2025年成绩斐然,但站在专业金融评论角度,仍需保持审慎理性。展望未来,全球高利率环境的延续性、大国博弈下的合规审查趋严、以及来自新加坡等兄弟枢纽的激烈竞争,仍是香港必须面对的长期考验。监管机构与从业者需继续深化虚拟资产(Virtual Assets)、Web3金融及可持续金融(ESG)等新兴领域的制度建设,进一步提升离岸人民币流动性池与衍生品供给,方能强化香港在全球财富管理格局中的长期核心竞争力。
Despite stellar 2025 results, a rigorous financial critique warrants a prudent look ahead. Moving forward, prolonged global rate environments, heightened regulatory compliance amidst geopolitical frictions, and intense regional competition from sibling financial hubs remain structural challenges. Regulators and industry practitioners must continuously refine market frameworks in digital assets, Web3 finance, and sustainable finance (ESG), while deepening offshore RMB liquidity pools and risk-management tools to cement Hong Kong's enduring competitive edge.
免责声明 / Disclaimer
本文仅作为一般概述,旨在提供信息参考,并基于有关证监会通函的公开资料编写。它不构成任何法律、监管、合规或专业建议。读者不应依赖本概述来代替审阅完整的官方通函及相关文件,亦不应代替寻求合格专业人士的独立意见。文中所载资料可能并不完整或并非最新,且监管要求可能会发生变化。对于基于本文内容所采取的任何行动或引起的任何遗漏,概不承担任何法律责任。持牌实体应直接咨询证监会或其自身的法律/合规顾问以获取具体指引。
This article is a general summary prepared for informational purposes only and is based on publicly available information regarding the SFC circulars. It does not constitute legal, regulatory, compliance, or professional advice. Readers should not rely on this summary as a substitute for reviewing the full official circulars and associated documents or obtaining independent advice from qualified professionals. The information may not be complete or up to date, and regulatory requirements can change. No liability is accepted for any actions taken or omissions based on this content. Licensed entities should consult the SFC directly or their own legal/compliance advisors for specific guidance.
原文(Source):https://apps.sfc.hk/edistributionWeb/gateway/TC/news-and-announcements/news/doc?refNo=26PR103